


Building insurance
Homeowners insurance covers damage to your home and yard caused by events such as fire, burglary, storms, and lightning. All fixtures—such as a built-in kitchen, hardwood floors, and a shed—are covered by homeowners insurance.
Calculate Your PremiumNever Underinsured
Put together your own package for your dream home
A wide selection
We compare many insurance companies for you, which saves you time
Help from our experts
Can't figure it out? Our experts are always ready to help you
Everything You Need to Know About Homeowners Insurance
Homeowners insurance, or “home insurance,” is a type of insurance that covers damage to your home. “Structure” refers to everything that is permanently attached to the house. Removing these parts of your home would require demolition or dismantling.
These include windows, ceilings, pipes, central heating, the bathroom, doors, and walls. Fences, garden gates, hedges, and planted trees are also considered part of the structure.
Freestanding items that you take with you when you move, such as a washing machine, a freestanding bathroom cabinet, or curtains, are considered part of your household goods.
Your Homeowners Insurance Coverage
All-Risk
- Fire damage
- Burglary and Vandalism
- Damage Caused by Adverse Weather Conditions
- Damage caused by sudden, unforeseen events

Comprehensive Insurance, Home Contents Insurance
With comprehensive household contents insurance, you’re well covered against most types of damage. For example, you’re covered for damage caused by an explosion, fire, lightning, or a fallen tree. The costs of preventing further damage or cleaning up the damage are often reimbursed as well.
If you have comprehensive home insurance, these costs are usually reimbursed up to a certain amount. With this insurance, you’re also covered for damage caused by unexpected events. Even if you accidentally cause damage to your home yourself, you’re covered.
In addition, there is storm damage (starting at wind force 7), water damage, theft, and damage caused by burglary are covered. This applies even if nothing was stolen and there is only damage caused by forced entry.
This is covered under a home insurance policy
Homeowners insurance covers various types of damage. If you cause this damage to your home yourself, you are still covered under the all-risk policy.
You can cover the following types of damage with home insurance:
smoke and soot damage
damage caused by an explosion
flooding (no levee breach)
lightning strike
precipitation and frost
In most cases, damage is covered only if it results from an “unforeseeable event.” Damage caused by, for example, an earthquake, a nuclear reaction, or a volcanic eruption is excluded under the terms and conditions.
Glass Insurance as a Supplement
The windows of a home are often not automatically covered under standard insurance policies, but you can insure them separately. To do so, take out a glass insurance policy.
Be sure to carefully review the terms and conditions and exclusions, especially if your home has unique features such as stained glass.
Calculate the Value of Household Goods
When you take out home insurance, you need to know how much your home is worth. This refers to the replacement cost: the amount you would need to rebuild your home exactly as it is now.
The rebuilding cost calculator makes it easy to calculate the replacement cost of the building.
The foundation of the house is not included in this coverage. If the foundation is damaged, a new foundation must be built when the house is rebuilt. With most home insurance policies, you can include the foundation in your coverage for an additional premium.
Avoid underinsurance with the replacement cost calculator
You areunderinsuredif the actual replacement cost of your home is higher than the amount you have insured it for. This can cause problems in the event of damage.
Many insurers offer coverage against underinsurance. In such cases, you’re often required to complete thereplacement cost assessmentat predetermined intervals. This is usually once every 5 years.
Calculation Example: Underinsurance
Suppose you have home insurance coverage of €150,000 and it costs €300,000 to rebuild the house. In that case, you are insured for 50% of the value. If there is damage, you will therefore only be reimbursed 50% of the amount of the damage, regardless of how much damage there is.
Homeowners Insurance Is Required for a Mortgage
Homeowners insurance is useful and often required when you take out a mortgage. A fire can (seriously) damage your home and cause a lot of problems. In some cases, you might end up without a home but still with a large mortgage debt. That’s why the bank usually requires you to have homeowners insurance.
Homeowners Insurance by Property Type or Situation

Apartment
Whether you need home insurance for your apartment depends on whether you own or rent it.
- If you've bought an apartment, you're responsible for obtaining building insurance for your apartment. Sometimes you have to arrange this yourself; other times, the Homeowners' Association (VVE) handles it for you. Read more about building insurance for the VVE.
- Have you rented an apartment? If so, you don't need to take out building insurance yourself. That's because the owner of your apartment is the landlord and is therefore responsible.
You are responsible for paying for damage to your personal belongings, such as furniture and clothing. Therefore, be sure to add “owner’s coverage” if you buy a home, or “renter’s coverage” if you rent, to your household contents insurance policy.
Rental Home
If you rent a home, do you still need to get home insurance? In that case, the landlord is responsible for getting home insurance. So you don’t need to get home insurance yourself.
To protect your belongings, you can take out home contents insurance. This covers items such as your furniture and clothing, so you can be sure you’re fully insured in the event of, for example, a fire or water damage.
New Construction
It doesn't matter whether you're buying a new home or an existing home when it comes to home insurance. The coverage remains the same. The timing of when you purchase the insurance doesn't change either. Make sure you've arranged all the necessary insurance policies before you receive the keys.
If you buy an existing home, the current residents are responsible for the insurance until you receive the keys. If you buy a newly built home, there are no residents yet. In that case, the construction company building the home is responsible for it until the keys are handed over.
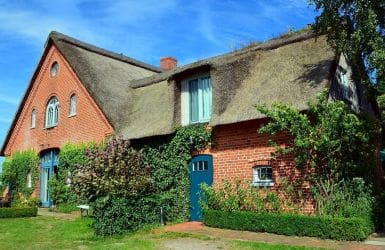
Thatched-roof house
A thatched roof comes with an increased risk of fire and storm damage. Fortunately, you can purchase property insurance for your thatched roof. Thatched roofs are, in fact, covered under a property insurance policy.
Compare the terms and conditions of different insurers. An insurer may charge a higher premium or have different terms and conditions due to the higher risk associated with a thatched roof.
Excess Amount for Homeowners Insurance
You can find affordable home insurance by comparing different insurers. You should also consider the deductible. Every insurance policy may include a deductible. A deductible means that, in the event of a claim, you are responsible for paying a portion of the damages yourself.
A distinction is made between a mandatory and a voluntary deductible. Homeowners insurance policies usually do not include a mandatory deductible. If one is included, it is often around €100 or €150.
With some insurers, you can choose whether to have a deductible and how much it will be. The rule is: the higher your deductible, the lower your premium.
We compare different insurance companies


Never Underinsured
Create Your Own Package
A wide selection
We compare all insurance companies for you, saving you time
Help from our experts
Can't figure it out? Our experts are always ready to help you
Frequently Asked Questions About Homeowners Insurance
What is home insurance?
Homeowners insurance is a type of insurance that covers damage to your home. The term “home” refers to everything that cannot be removed without causing damage to your home. A wide range of potential causes of damage is covered.
What exactly is covered by building insurance?
Homeowners insurance covers everything that is attached to the house, such as plumbing, central heating, the bathroom, and the toilet. Damage you cause yourself is not covered under standard coverage; for that, you need comprehensive coverage.
Damage is covered in the event of an “unforeseen incident,” but not in the event of earthquakes, nuclear reactions, or volcanic eruptions. Be sure to review the terms and exclusions carefully.
Why Get Homeowners Insurance?
Damage to your home can quickly become expensive. For example, if a fire breaks out in the kitchen due to a short circuit, or if the bathroom is flooded because of a broken faucet. With home insurance, you don’t have to worry about this, because these kinds of situations are covered.
What does "replacement cost" mean in the context of building insurance?
To get home insurance, you need to calculate the replacement cost of your home. The replacement cost is the amount needed to rebuild your home in the same location and in the same way. This amount is the maximum the insurer will pay out. Since the location and land on which your home stands are not lost in the event of damage, you do not need to insure them. As a result, the replacement cost is lower than the market value.
Is water damage covered by home insurance?
In principle, water damage is covered by homeowners insurance, but there are a number of conditions attached. For example, the damage must be caused by one of the following:
- Due to leaks in the central heating system, water pipes, or connected systems.
- Due to leaks caused by central heating or water pipes bursting from freezing.
- Damage caused by a leak at a neighbor’s home is not always covered. If your home insurance does not provide coverage for this, you may be able to recover these damages through your neighbor’s liability insurance.
- Due to leaks in roofs or gutters.
- Storm-related water damage.
Is storm damage covered by home insurance?
Yes, storm damage is covered under a home insurance policy. However, you’ll have to pay a deductible before you receive compensation for the damage. This amount is higher than for other types of damage. Typically, you’ll pay two-thousandths of the amount for which you’ve insured your home as a deductible. This amount usually ranges from €200 to €500 but varies by insurer.
How much does home insurance cost?
The annual cost of home insurance varies by household. Unique properties may have different terms and premiums. The average premium is €1.30 per €1,000 of insured value. For a home with a replacement cost of €250,000, you’ll pay an average of €325 per year (€393.25 including insurance tax). Comparing policies can often lead to cheaper options.
How is the amount of my premium determined?
The premium you pay for home insurance varies by insurer and depends on the following factors:
- The construction value of your home (roof and walls).
- Due to leaks in the central heating system, water pipes, or connected systems.
- Due to leaks from frozen central heating or water pipes.
- Due to leaks in roofs or gutters.
Clear, transparent, and honest advice for over 110 years
 customer testimonials
We'd be happy to help you right away
Having trouble figuring it out online? We're happy to help you via chat or WhatsApp.
 Ask your question and get a response within 2 minutes